Specialist Supported Housing vs Buy-to-Let 2026 | The Advice Room
Investor Guide · 2026

Specialist Supported Housing vs Buy-to-Let

The risks, the rewards, built versus off-plan, and where in the UK each strategy actually performs. An honest side by side comparison for investors weighing income against control.

Premium residential interior
5.5–9%BTL gross yields, 2026
CPI-linkedSSH lease income
20 yrsReal estate experience
The two models

Similar on paper. Different in every way that matters.

Both involve owning a residential property and collecting rent. In practice they behave like separate asset classes, with different income mechanics, risk profiles and exit routes. The core question is simple: who does your income actually depend on?

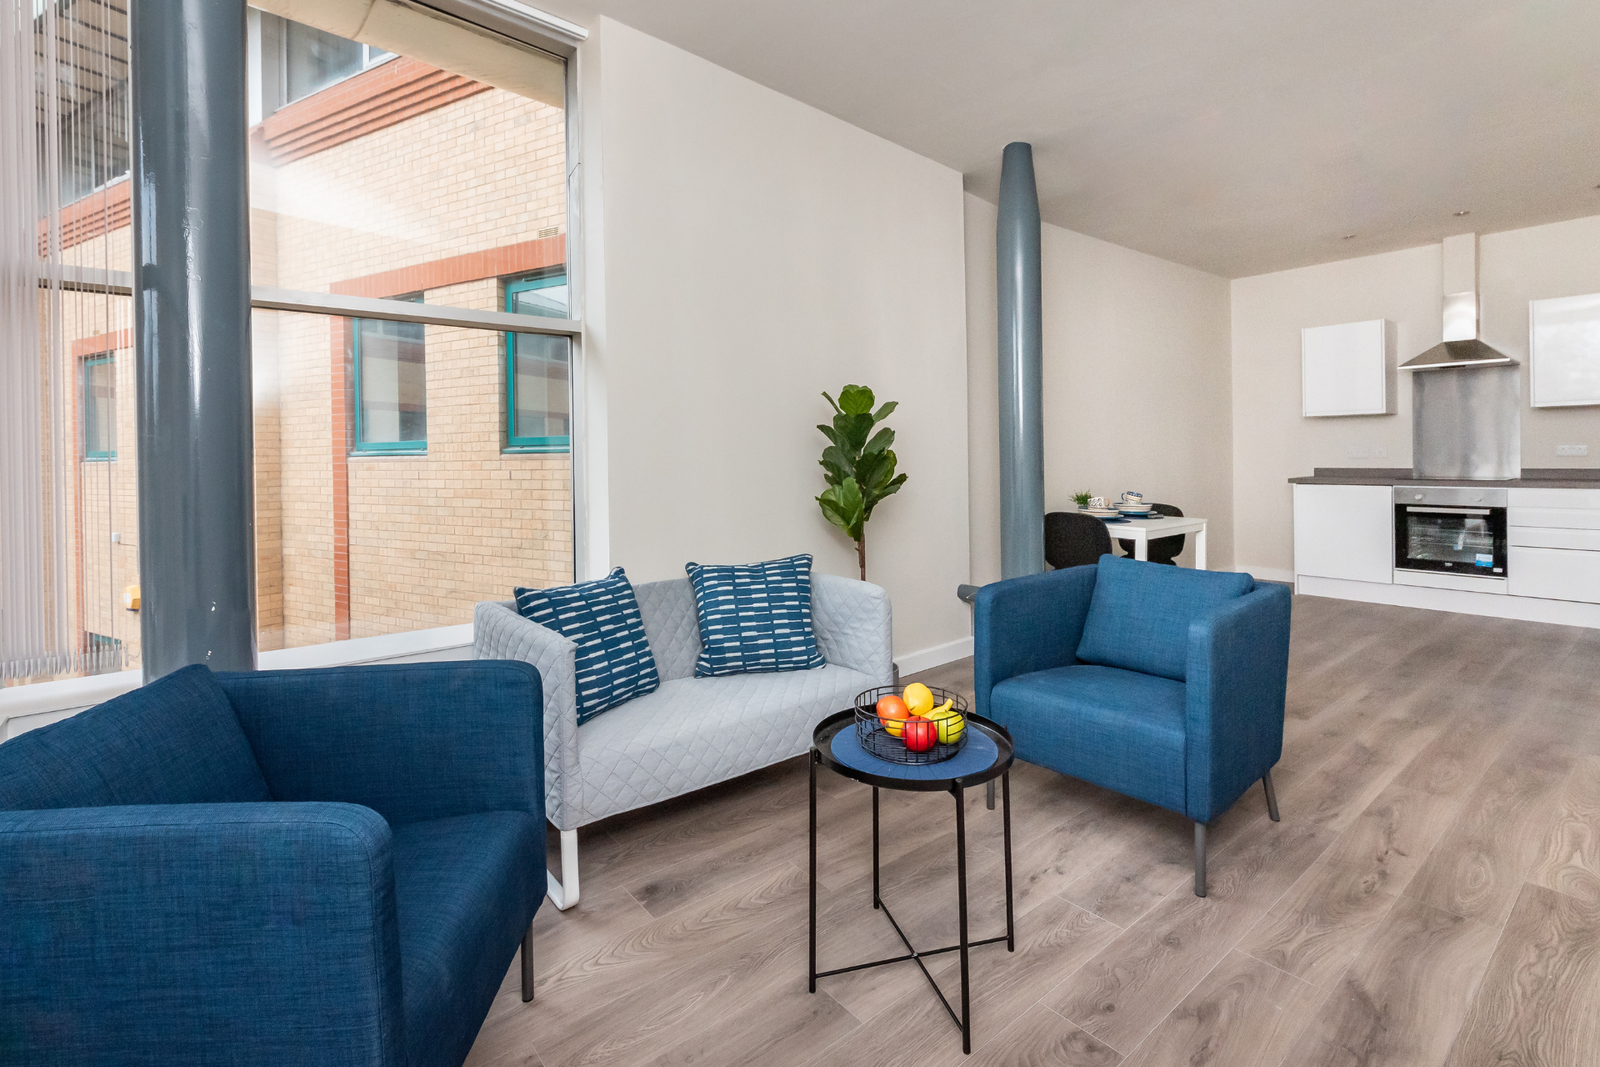
Specialist Supported Housing interior
Specialist Supported Housing

Contracted income, completely hands off

Accommodation for people who need extra support to live independently: older people, adults with physical or learning disabilities, people living with mental health conditions, autistic adults, and those with complex housing histories.

The property is leased long-term to a Registered Provider, a housing association or similar body formally registered with, and regulated by, the Regulator of Social Housing. They hold the lease and take responsibility for the tenancy, while an experienced support operator handles the care and day-to-day management.

For you as the owner, that means completely hands off: no tenant sourcing, no rent chasing, no maintenance calls, no void management. You own the asset and receive the rent.

Your income depends on a lease and the strength of the counterparty behind it.
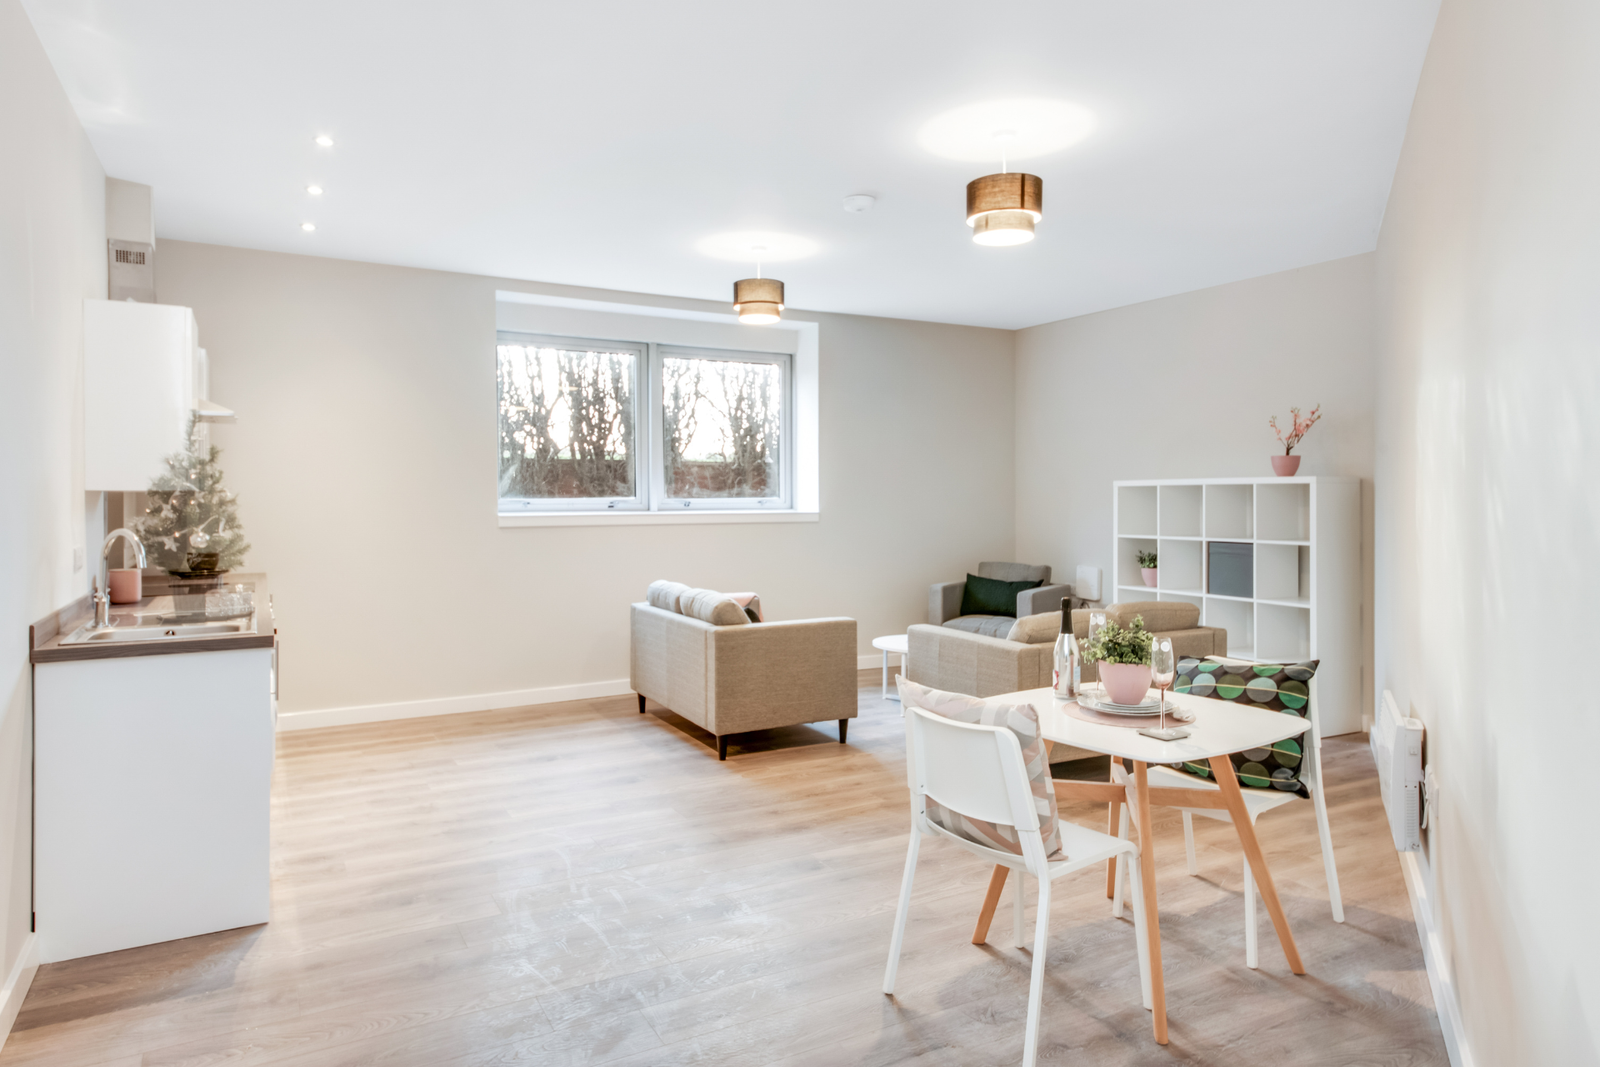
Buy-to-let apartment interior
Traditional Buy-to-Let

Open-market letting, full control

You buy, you let, and your return rides on local rental demand, void periods, mortgage costs, maintenance and capital growth. You keep complete control of the asset, and complete responsibility for it.

Your income depends on the open rental market and how you manage it.
Rewards compared

Where each one pays

FactorSpecialist Supported HousingTraditional Buy-to-Let
Income sourceLong-term lease to a Registered Provider, often government-fundedOpen-market tenant rent
Rent stabilityFrequently inflation-linked (CPI), fixed for the lease termSubject to demand, arrears and voids
Void riskRent usually paid regardless of occupancy under the leaseLandlord absorbs empty periods
Entry pointCash-only investment, no mortgage route availableLower entry point, mortgage finance widely available
ManagementFully outsourced to the operator, completely hands offLandlord or agent, hands-on
Capital growthMore muted, income-led rather than growth-ledStrong potential in the right location
Liquidity & resaleThin, specialist market, harder to exitDeep open market, easier to sell
Social impactDirectly houses vulnerable peopleNeutral

SSH is powered by structural demand, an ageing population, rising recognition of mental-health and learning-disability needs, and chronic undersupply, so its contracted, index-linked income is designed to shrug off the voids and churn that erode buy-to-let returns. Buy-to-let, in turn, offers what SSH rarely matches: a liquid, flexible asset with real capital-growth potential and gross yields of roughly 5.5 to 6 percent nationally, far higher in the right cities.

Risks compared · the honest version

No strategy is risk-free, and SSH is often sold more confidently than the fundamentals justify.

Supported housing propertySSH risks
  • Counterparty risk is the big one. If the provider fails or exits, income stops, and re-letting to the standard market is difficult, with long, costly voids.
  • Illiquidity. The resale market is thin. On exit, the property is often valued nearer its vacant possession value than the price you paid.
  • Overpricing. Some SSH stock sells for considerably more than the property's vacant possession value. Overpay, and your real risk begins the day the lease ends.
  • The headline lease is not the real lease. A "25-year" term can hide break, performance and funding clauses. Read the exit terms.
  • Regulation gaps. Insist the support is properly regulated: CQC for adults, Ofsted for children's.
Buy-to-let apartmentBuy-to-let risks
  • Tax drag. Section 24 replaced full mortgage-interest relief with a 20% credit, pushing many higher-rate landlords into a larger bill. Limited-company ownership is now the default for leveraged portfolios.
  • Purchase costs. The stamp duty surcharge on additional property rose from 3% to 5% in England and NI (higher again in Scotland and Wales), and companies pay it too.
  • Capital gains. The annual CGT allowance has been cut to £3,000.
  • Regulation. Minimum EPC of E and rising, plus the Renters' Rights Act removing no-fault evictions.
  • Operational risk. Voids, arrears, maintenance and mortgage-rate exposure all sit with you.
The takeaway: SSH can deliver hands-off, index-linked income, but only when the counterparty, the lease and the price all stack up. A weak version of SSH is riskier than a solid buy-to-let, not safer.
Built vs off-plan

The same choice applies to both models

Whether you buy SSH or buy-to-let, you can buy a completed asset or one bought before it is finished. This decision shifts your risk and return more than most investors expect.

Built / completed

  • Income from day one, or from lease commencement in SSH.
  • You inspect the actual asset, not a CGI or a brochure.
  • No construction risk and no reliance on a developer completing.
  • Usually a quicker route to a producing asset.
  • Trade-off: today's price for today's value, with less built-in uplift.

Off-plan

  • Priced below completion value. Commit at today's price on an asset completing in 1–3 years; strong regen markets have delivered double-digit uplift.
  • Staged commitment and first pick of the best units.
  • Developer delivery risk. More schemes are stalling in 2026; recovering staged payments can be slow.
  • Down-valuation. If completion valuation lands low, you bridge the gap in cash.
  • Optimistic projections. Apply a 10–15% haircut to marketed rents; no income until completion.
Rule of thumb: off-plan suits growth-led investors who can wait and who buy only tier-one developers in supply-constrained cities. Completed stock suits income-first investors who want lower uncertainty and an asset they can assess today. For SSH specifically, off-plan can work well, but confirm the lease and operator are locked in, not merely "expected".
Locations

They follow two completely different maps

This is where the strategies diverge most, and where investors most often get it wrong.

Supported housing location
SSH · the need map

Follows local-authority demand

SSH demand is created by commissioning need and the presence of Registered Providers, not open-market rent. The strongest opportunities line up genuine demand, a provider with covenant strength, and suitable stock at a sensible price.

Commissioning needProvider strengthAdaptable stock
Buy-to-let location
BTL · the yield map

Follows the rent-to-price ratio

In 2026 the strongest gross yields sit in the North, Scotland and select port and university cities. London trades yield for resilient demand and long-term capital growth.

Southampton ~9%Aberdeen ~8.6%Hull ~8.4%Manchester ~7.8%Liverpool ~7.4%

Under the Supported Housing (Regulatory Oversight) Act 2023, every local authority must publish a supported-housing strategy by May 2027. Those strategies are effectively a published demand signal, a far better guide to SSH location selection than any yield table.

Which suits you?

Match the model to the investor

Choose SSH if you want
  • Cash available to buy outright. SSH is a cash-only purchase with no mortgage route, so it suits investors deploying capital rather than leveraging it
  • Completely hands-off, contracted, inflation-linked income with no tenant or void management
  • A longer horizon and comfort with lower liquidity
  • Exposure to a socially useful, demand-resilient sector
  • Predictability over capital growth
Choose buy-to-let if you want
  • A lower entry point, or to use leverage. Mortgage finance lets you spread capital across more than one property rather than committing it all to a single asset
  • Control, flexibility and a liquid, easily sold asset
  • Meaningful capital-growth potential
  • The ability to tax-plan, typically via a limited company
  • Comfort with market cycles and hands-on responsibility

Many experienced investors run both: buy-to-let for growth and liquidity, SSH for stable, contracted income that smooths the portfolio.

Before you commit

The SSH due-diligence checklist

Take one thing from this page, take this. It is the difference between a resilient SSH asset and an expensive mistake.

Who is the lessee?

Check the Registered Provider's financials, regulatory standing and track record.

Is the support regulated?

CQC for adult care, Ofsted for children's services. Non-negotiable.

Read the full lease

Term length and every break, performance and funding clause, not just the headline.

Confirm the rent basis

Is it genuinely CPI-linked and backed by durable funding?

Check repairing obligations

Who pays for repairs and specialist adaptations across the term?

Get an independent valuation

Compare the asking price to the RICS vacant possession value, not the "investment" price.

Understand the exit

Is there a real secondary market or a credible buy-back, or are you locked in?

Use your own advisers

Your own solicitor and an independent financial adviser. Never the sales side alone.

See opportunities that pass genuine due diligence

Tell us your goals and we will walk you through vetted, fully managed Specialist Supported Housing, and where buy-to-let makes more sense, we will say so.

Speak to the team 01925 943950
The Advice Room

Quality property, assured rents. We connect investors with fully managed Specialist Supported Housing across the UK.

Get in touch
01925 943950 info@theadviceroom.co.uk

Unit 7, Olympic Way,
Warrington, WA2 0YL

The Advice Room is a trading style of Luxury Invest Group. The purpose of this website is to provide you with information regarding the purchases of buy-to-let property and should not be interpreted as advice. When considering a property purchase, we recommend carrying out appropriate due diligence and seek independent legal advice prior to purchasing. This type of property is not classed as a regulated investment, therefore the Financial Services Compensation Scheme and Financial Ombudsman Service arrangements do not apply. The Advice Room does not offer or provide tax or investment advice and should you require advice, please speak with an independent financial advisor or tax advisor.

© Copyright 2026. All Rights Reserved. The Advice Room.